Stablecoin was a term you only heard in the crypto-trading community. It’s now showing up in CFO meetings, treasury roadmaps and bank strategy decks. Part of that is regulation catching up. The GENIUS Act, signed into U.S. law in July 2025, finally gave payment stablecoins a real legal framework, and regulators spent 2026 turning that law into working rules. Some of it is economics: businesses are tired of overpaying and waiting too long to move money across borders.
This guide is for those who want to do something with stablecoins – not speculators, but finance teams, payment product managers and bank operators, who have one question: is this faster or cheaper for our business and how do we get started?
What is a stablecoin transaction?
A stablecoin is a digital token that’s pegged to something stable, almost always the U.S. dollar and backed 1:1 by reserves like cash and short-term Treasuries. A stablecoin transaction is a transfer of that token from one wallet to another: a business paying a vendor in Vietnam, a bank moving overnight liquidity, a marketplace paying out sellers.
What’s different from sending dollars the old way isn’t the dollars, it’s the infrastructure underneath. Rather than going through a chain of correspondent banks, each charging their own fee and adding their own delay, the transfer happens directly on a blockchain and settles in minutes, not days. It’s also recorded on the blockchain, so it’s traceable and auditable in a way that wire transfers typically are not.
Benefits of stablecoins for corporate payments
If you ask a treasury team why they are piloting stablecoins, you’ll typically hear a few variations of this:
- Fast. Cross-border wires can take 2-5 business days depending on the corridor. Stablecoin payments settle in minutes and are available 24/7 with no cut-off times.
- Price. This is the main one. That’s why so many finance teams are so focused on how stablecoins reduce transaction costs for financial institutions by eliminating most of those middlemen: every hop in a correspondent banking chain takes a cut. Transaction fees on a well-run stablecoin payments platform are often a tiny fraction of what a traditional international wire costs especially for high-value or high-frequency corridors.
- The predictability. In the case of FX and correspondent banking, the actual landed amount can be obscured by spreads and intermediary deductions until it arrives. Stablecoin settlement and local conversion offer businesses much greater clarity about what they are actually paying and receiving.
- A fourth benefit that receives less attention, but is just as important to CFOs, is working capital. Faster settlement means faster capital release, a real difference for a marketplace paying thousands of sellers or a manufacturer negotiating tight terms with overseas suppliers.
Interbank Transfers: Comparing Stablecoin Settlement Solutions
Banks considering stablecoin settlement for interbank transfers usually look at three approaches:
- Public stablecoin networks (USDC, USDT, etc.) – Deep liquidity, broad support across exchanges and payment providers, but banks rely on third party issuer’s reserves and redemption process.
- Bank-issued stablecoins – A bank or consortium of banks is issuing its own token on a closed, permissioned network. More control and certainty of compliance, less reach and liquidity than public networks.
- Tokenized deposits – not technically stablecoins, but they’re often lumped together. A tokenized bank deposit based on similar rail technology that remains tightly bound to existing banking regulation.
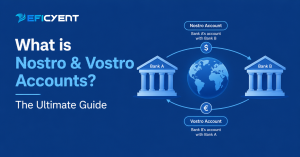
The interbank case is simple: correspondent banking today means pre-funding nostro accounts in various currencies and the opportunity cost of idle capital. With stablecoin settlement, banks can move value almost instantly, rather than parking so much dead capital around the world. Active management of counterparty risk and liquidity risk remains a must; this is a different track, not a way around treasury discipline.
The infrastructure layer: APIs, wallets, and stablecoin-as-a-service
None of this works without infrastructure and that’s where most of the actual construction is going on:
- Stablecoins wallets can be custodial (by a provider), non-custodial (where the business holds its own keys) or hybrid. Most corporates will start with a custodial wallet with a licensed provider, as managing private keys in-house is a security and operations burden that most finance teams aren’t set up for.
- A stablecoin API lets a company plug stablecoin movement into its existing systems issuing payouts, checking balances, converting to local currency, running compliance checks without anyone needing to ever touch a blockchain explorer directly. A good stablecoin API is just another payment rail in the existing stack.
- Stablecoin as a service puts it all together: a provider offers the wallet infrastructure, compliance, liquidity and on- and off-ramps to local currency so a bank or business does not have to build any of it from the ground up. As the GENIUS Act develops, with its specifications on reserve requirements, redemption schedules, and AML procedures, outsourcing this layer to a specialist seems more practical than building it in-house.
- Wallets, APIs, compliance and liquidity providers working together make up the generally called stablecoin payments infrastructure the pieces that actually move value and convert it into something a business can use.
How to use stablecoins – a practical introduction
- Choose a use case, not a technology. Pick one specific continuing problem to solve, whether it’s cross-border payments to suppliers, payouts to marketplace sellers, or treasury liquidity for an affiliate. Don’t try to change everything at once.
- Pick a provider, not a chain. If you don’t have a crypto engineering team in-house, a stablecoin payments platform or a stablecoin-as-a-service provider can take care of custody, compliance and conversion for you.
- Wallets & on/off ramps. If a counterparty doesn’t want to receive payment directly in stablecoin, then you need to have a way to convert local currency in on one end and back out on the other.
- Integrate with the API. The least exciting step, and usually the easiest – a decent stablecoin API looks and feels like any other payments API you have already integrated.
- Run it alongside. Most treasury teams operate stablecoin rails alongside their existing payment method on a single corridor, using the old process as a benchmark for settlement time and stablecoin transaction costs before switching over.
The current regulatory environment
The GENIUS Act was the first real U.S. federal framework for payment stablecoins in mid-2025, including who can issue them, how reserves must be held, and how fast holders can redeem their tokens. The OCC, FDIC and Treasury have been working through the detailed rulemaking that implements its reserve and custody standards, anti-money laundering obligations and how state regulators fit alongside federal oversight through 2026. All of it is still in draft form and comment periods are open. Reserve, redemption and compliance requirements are likely to keep evolving, so companies building on stablecoin rails are best served tracking the rules themselves, rather than relying on summaries.
Something to remember is
There are no free lunches. Not all stablecoins are backed the same and this is what regulators are trying to standardize. Issuer quality and transparency matters. Liquidity is corridor and currency pair dependent and whilst the cross border leg may be fast and cheap the FX conversion in or out of local currency can still be expensive. None of that undermines the case for stablecoins, it just means treating this like any other payments infrastructure decision: pilot it, measure it and scale up when the numbers hold up.
The direction is clear enough: faster settlement, lower fees, and better visibility into where money actually is at any given moment. Once a finance team sees that working on even one corridor, it’s a hard combination to ignore.